Gas Storage
In the last years, operators of German and European gas storages have faced many challenges. The market was and still is characterised by excess capacities. This applies not only to the available working gas volume (WGV) but also to the injection and withdrawal capacity. In the figure below, the situation is illustrated for the available withdrawal capacity in Germany.
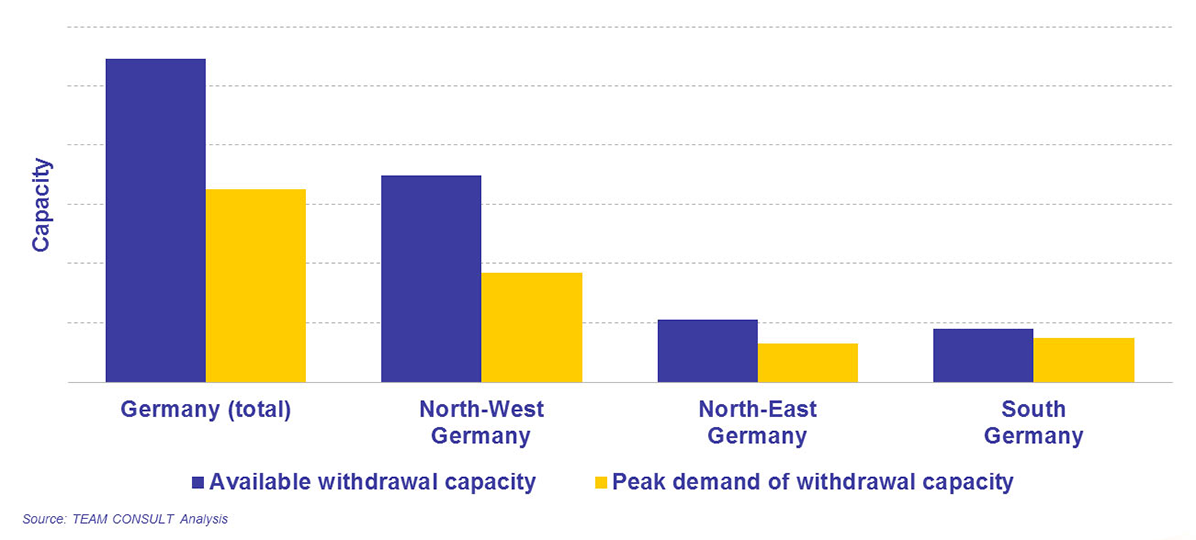
[Available withdrawal capacity and peak demand of withdrawal capacity (Illustration)]
Intense competition, changing market conditions and the combination of low variable and high capital costs – as it is typical in the asset business – has led to market prices that are, in many cases, nowhere near enough to cover the full costs of service. At the same time, the general perception is that gas storages carry substantial value, not only for fulfilling their “traditional” functions of providing seasonal swing and covering demand peaks. Gas storages also represent an insurance against unforeseen events by e.g. providing additional volumes and capacity in case of extreme weather events and production or transport failure. At the moment, however, this value cannot be monetised in the marketing of storage capacities.
Uncertain prospects
Different developments in the European gas market have opposing effects on the storage market and lead to great uncertainty regarding the future of storage assets. In the short- to mid-term, the European gas production is going to further decline and, thereby, the seasonal production swing. This is considered to increase the need for storage. On the other hand, the trend towards lower gas consumption reduces the need for storage. In the long-term, gas storages are sometimes expected to have a key role in the context of energy system integration – by offering a long-term and large-scale storage option for excess power production from renewable energies. To what extent gas storages will be used in the energy transition, largely depends on the conditions set by future energy policy and regulation.
Pressing questions
Under these circumstances, a number of key questions arise for storage system operators, storage users, storage owners, investors and, not least, for political actors:
- What are the factors influencing the development of the storage markets in Germany and Europe?
- How will storage utilisation, prices, revenues and costs develop?
- Which storage facilities would most likely overcome a consolidation phase?
- Are there undervalued storage assets which are worth acquiring?
- Are write-downs necessary for certain storage facilities and, if so, to what extent?
- Which are the storage products that will be profitable in the future?
- How should the political framework be set in order to ensure that neither a situation of excess nor shortage of gas storage capacity occurs in the future?
- How can the storage industry bring their concerns into the political discussion?
Consulting services
In this context, we offer the following consulting services:
- Benchmarking of gas storages
- Evaluation of investment and divestment projects
- Due diligence for investors
- Support in price revisions and arbitration proceedings concerning storage or flexibility service contracts
- Market analyses and development scenarios for the gas storage market
- Strategy development for storage operators
- Strategy development for storage operators
Publications
Storage fill levels (week 42)
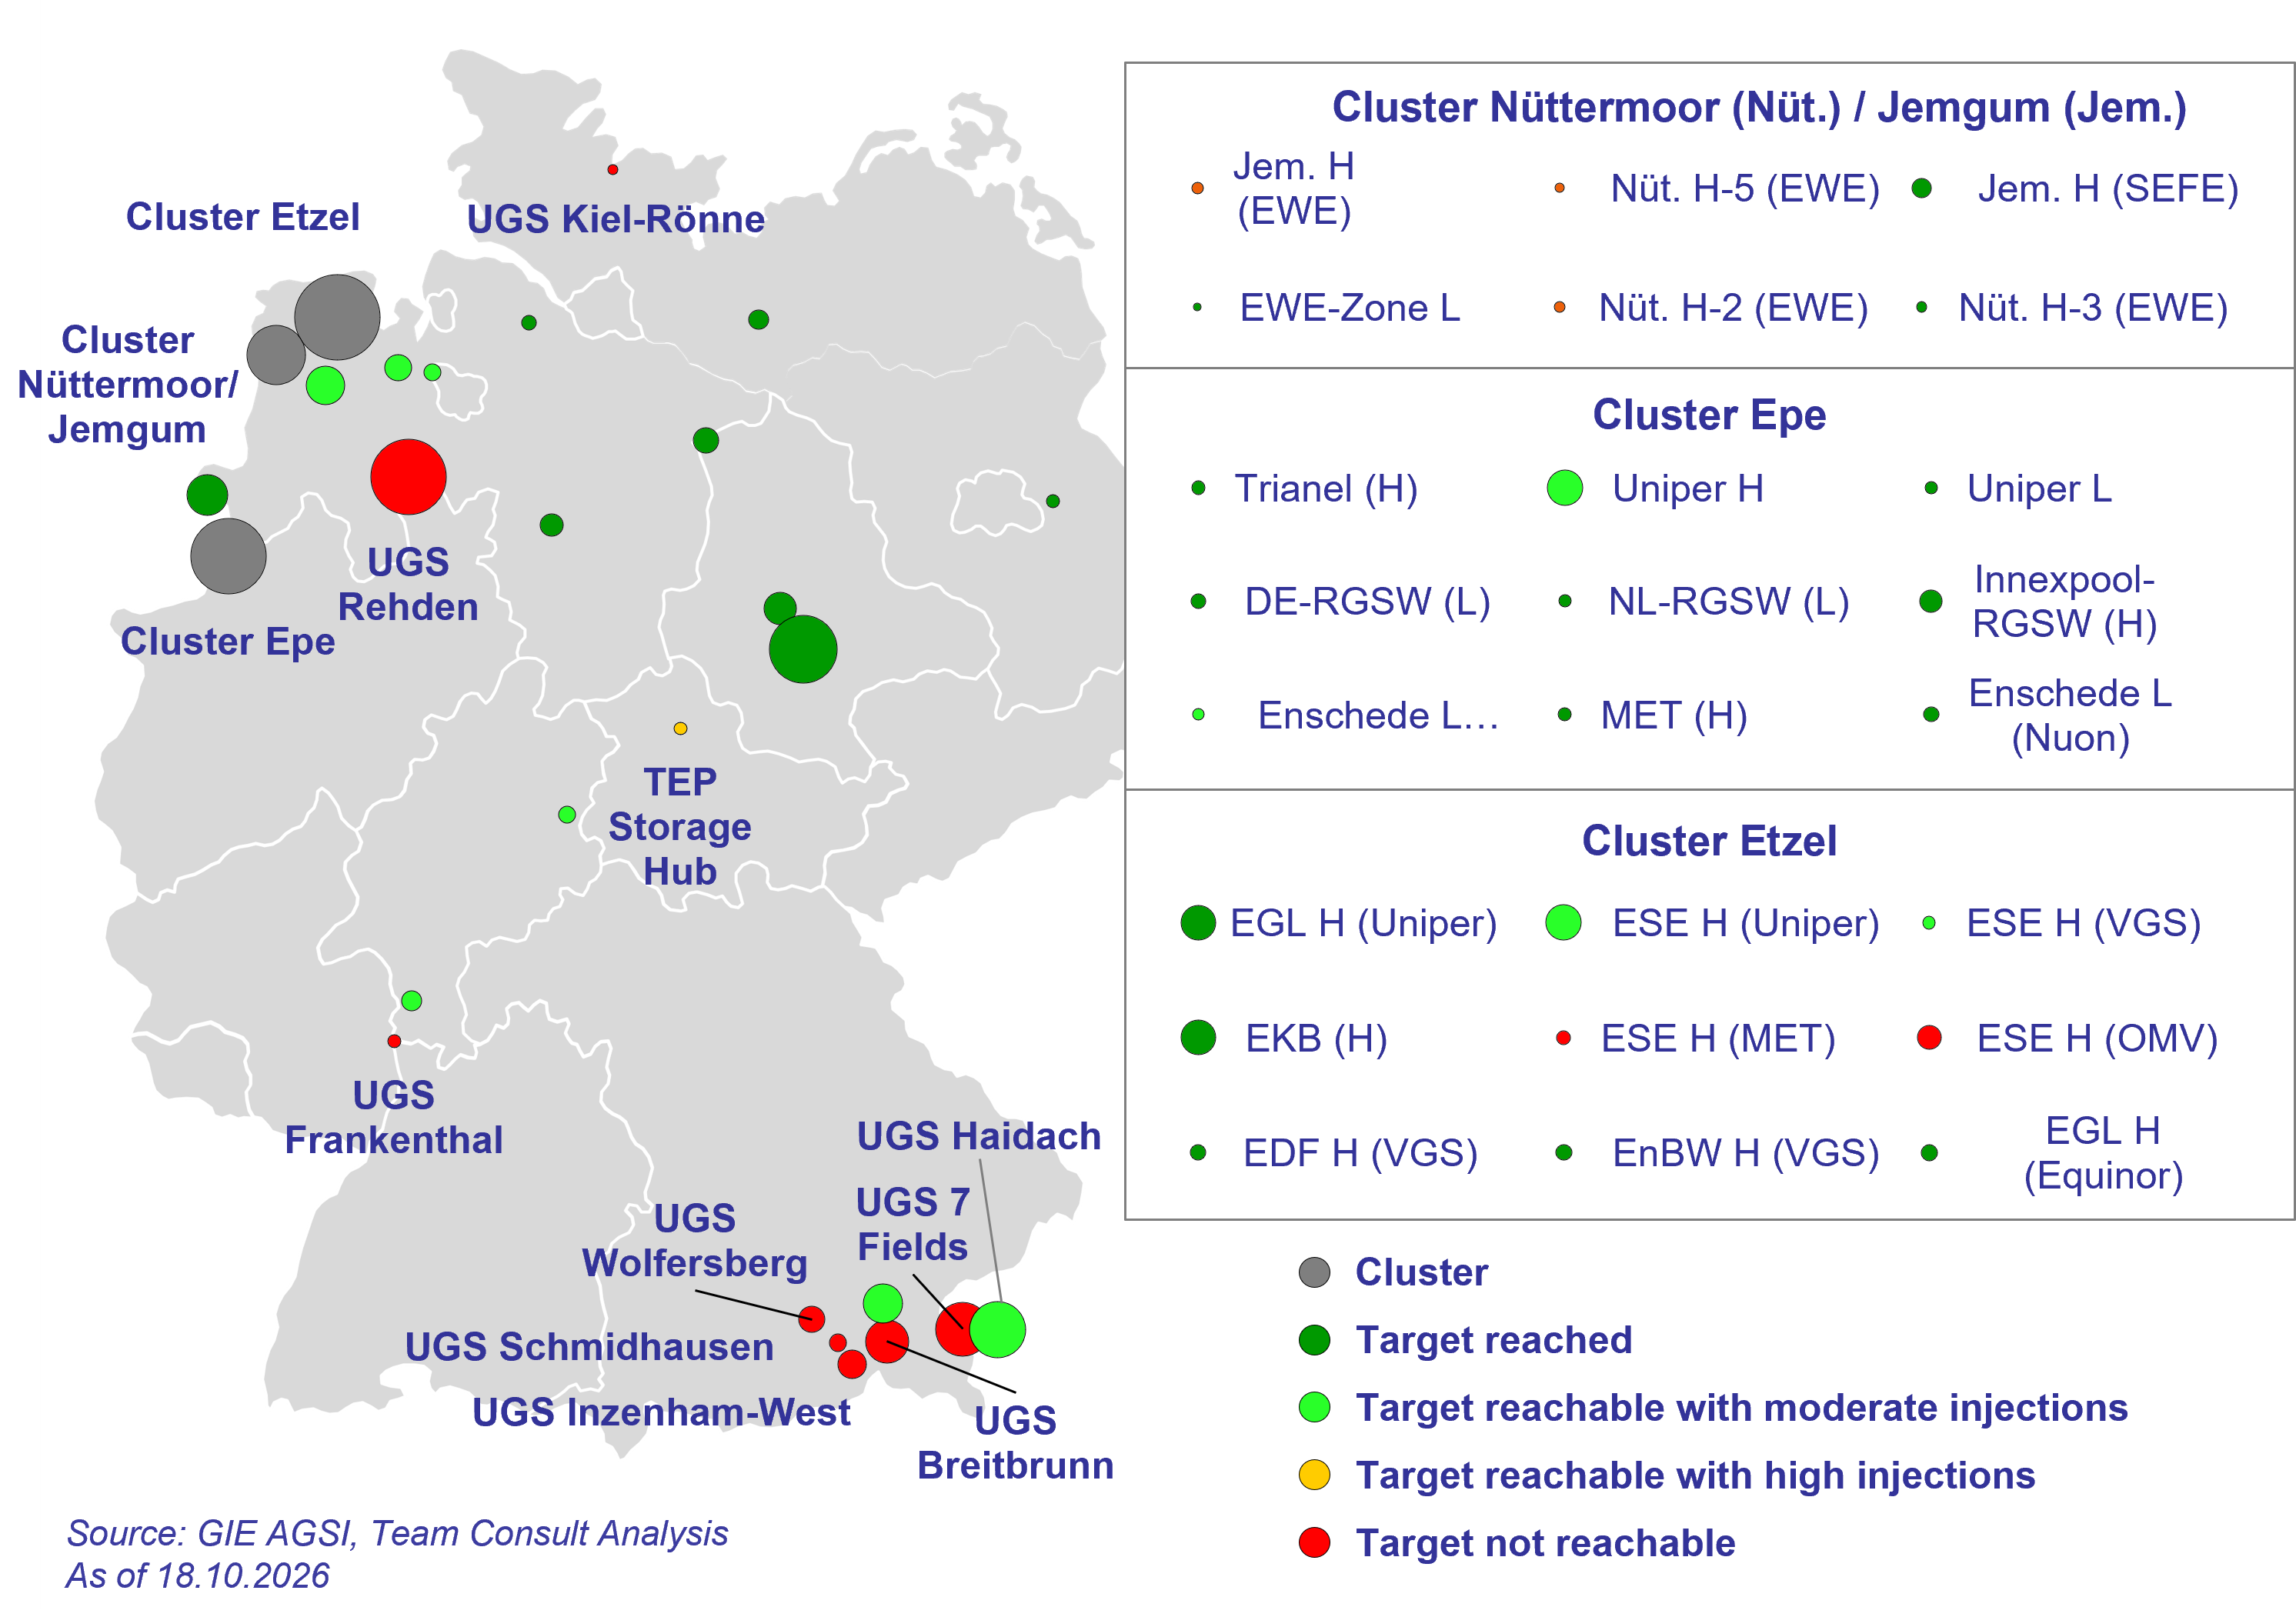
- Changes since last week:
- 6 storages have reached the targeted filling level: Innexpool RWEGSW, UGS Etzel EKB, UGS Etzel EnBW (VGS), UGS Harsefeld, VGS Storage Hub (Bernburg, Bad Lauchstädt, Katharina) and UGS Epe Uniper L-Gas,
- Due to withdrawals, the filling levels of 3 storages have fallen to below the targeted filling level: VGS Zone MND ESG (UGS Stockstadt + UGS Hähnlein), UGS Enschede Epe (Eneco) and VSP Nord (Rehden, Jemgum),
- 3 more storages can no longer reach the target: UGS Jemgum H (EWE), UGS Etzel ESE (OMV) und UGS Etzel ESE (MET). UGS 7 Fields can now only reach a filling level of 75%, however, German target filling levels don’t apply to Austrian gas storages.
- Net injections during 12.10–18.10: 2.38 TWh.
- Average filling level: 62.1%.
- Week-on-week average injections have fallen by 31%.
- 11 storages had a negative injection/withdrawal balance, 420.7 GWh were withdrawn across these storages, thereof 103 GWh in UGS Etzel EnBW (VGS), 76.6 GWh in VGS Storage Hub and 71.8 GWh in VGS Zone MND ESG.
- Gas storages in Germany and two storage locations in Austria (7 Fields and Haidach which are connected to the German transmission grid) are mapped and categorized regarding their prospects to reach the mandatory storage filling levels. Some storages are grouped into clusters if they are geographically close to one another (which is the case at three different locations: Epe, Etzel and Nüttermoor/Jemgum).
- 23 of 48 storages have already reached the target level (dark green category). Many storages are in the light green category, meaning that it is possible to reach the target filling level of the respective storage by November 1 if daily injections are made amounting to 75% of the technical injection capacity or less on average in the period remaining until November 1. Storages requiring daily injections of more than 75% of the technical injection capacity (on average from today until November 1) are in the yellow category.
- 12 of 46 storages in Germany can no longer reach the target filling level, even if technical injection capacity was fully used on every remaining day until November 1 (red category). These are five porous rock storages in Southern Germany, UGS Nüttermoor H-2 and H-5, UGS Rehden UGS Kiel-Rönne, UGS Etzel ESE (MET and OMV), UGS Jemgum H (EWE). Additionally, UGS 7 Fields can now only reach a filling level of 75%, however, German target filling levels don’t apply to Austrian gas storages.
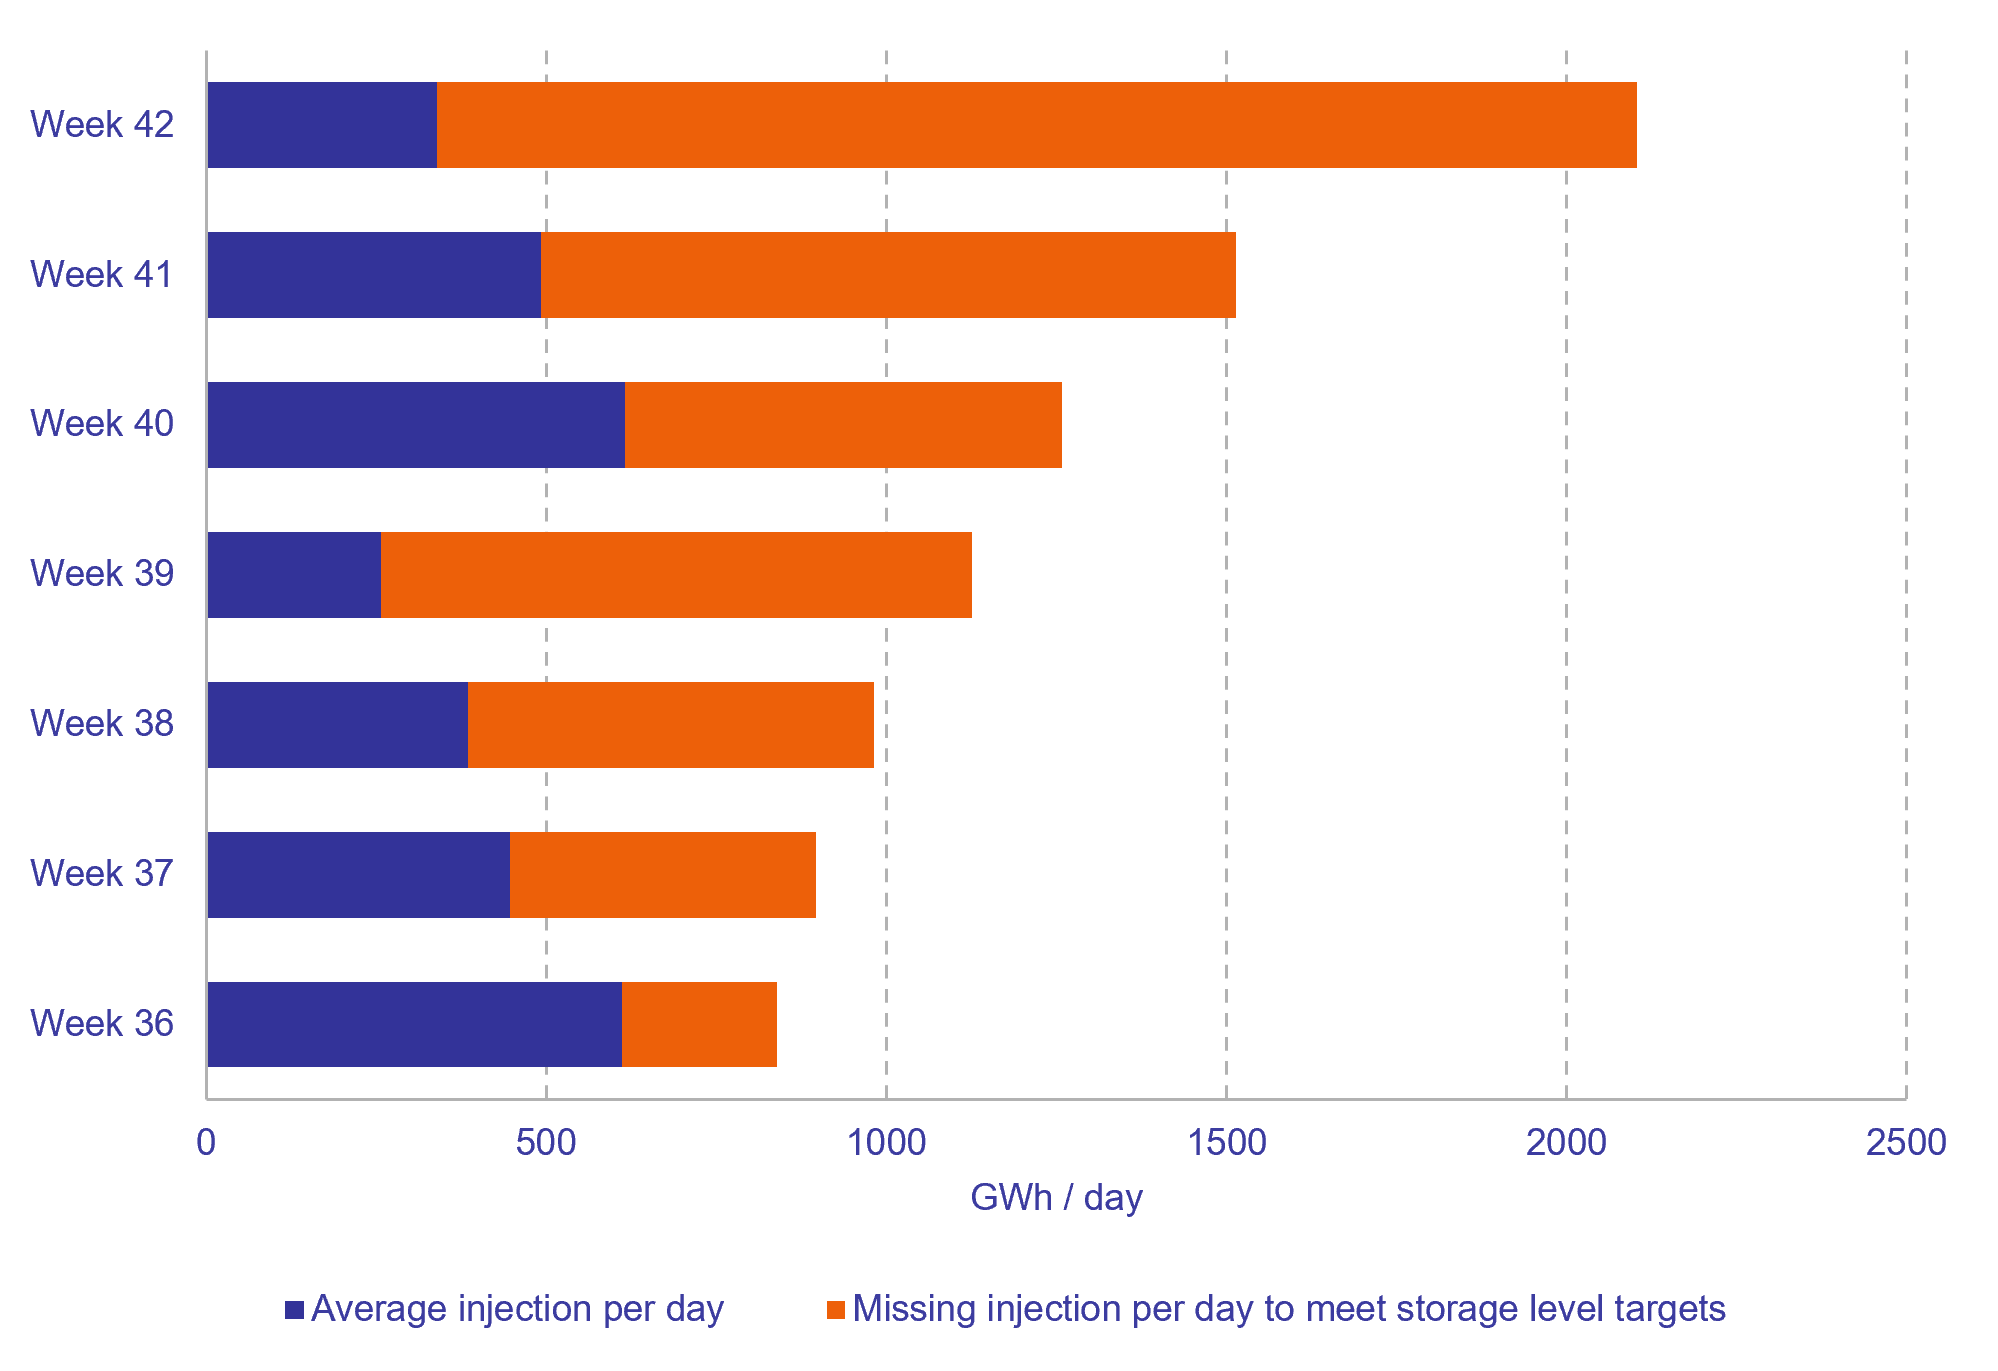
- Daily injections into underground storages in Germany have fallen by 31% week-on-week (currently 339.7 GWh/d on average over the past 7 days). The utilization of technical injection capacity remains low (10.7%). 2,103.5 GWh/d would be required on average until November 1 to meet the targets).
- The EEX-THE spot-market price is currently €0.65/MWh below the price for the Q1’27 contract, providing only a limited incentive for the injection of gas into storages.
- The price spread between JKM and EEX-THE incentivizes LNG deliveries to Europe rather than to Asia: the European market shows a premium of €8.07/MWh over Asia for November 2026. For December 2026 deliveries, the JKM price is €2.15/MWh higher that EEX-THE price, meaning the Asian market will be more attractive (as of October 16).
- If all storages in Germany were to reach their target fill levels exactly, this would result in a weighted average filling level of 71.4%. Assuming that the average daily injections remains at the level seen over the last 7 days, the filling level in Germany will reach only 63.6% by 1 November. If the average daily inflow remains at the level seen over the last 21 days, the filling level will reach 63 per cent.
Storage fill levels (week 40)
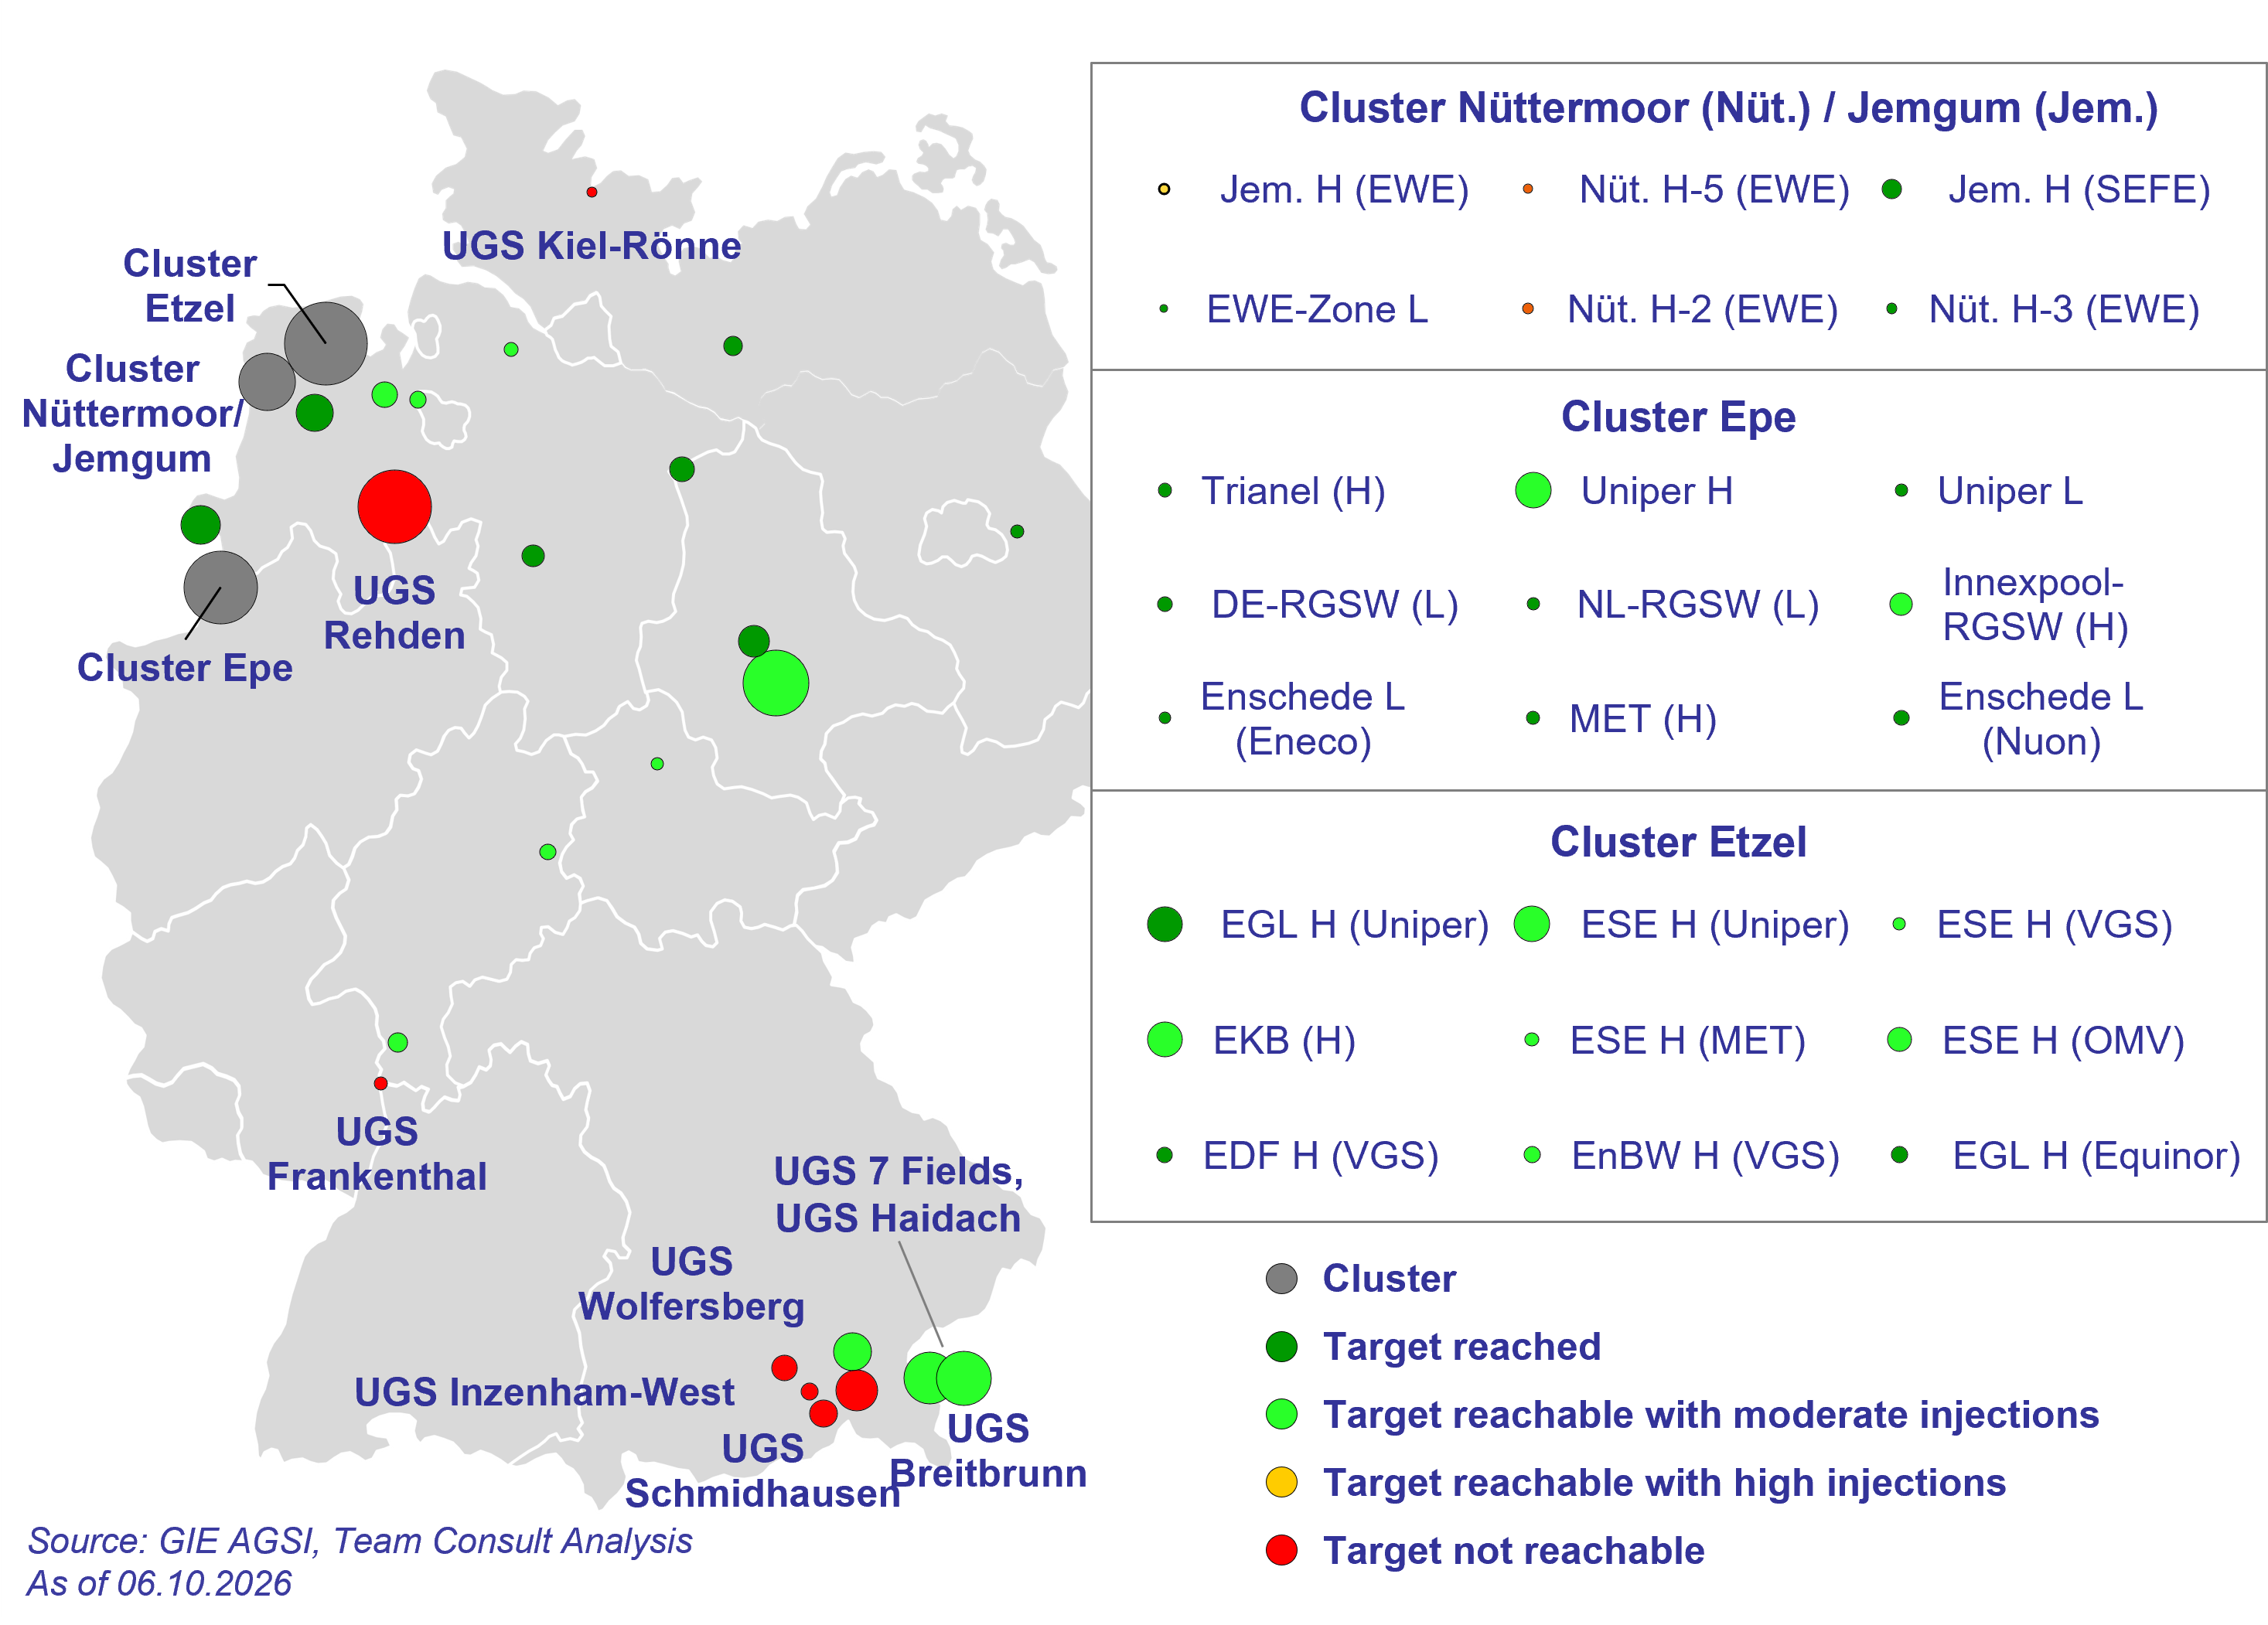
- Changes since last week:
- 1 storage has reached the targeted filling level (UGS Stassfurt),
- 2 more storages can no longer reach the target: UGS Kiel-Rönne and UGS Schmidhausen.
- Total injections during 30.09–06.10: 4.26 TWh.
- Average filling level: 60.4%.
- Week-on-week average injections have nearly doubled; however, utilization of injection capacity remains low (13%).
- 4 storages had a negative injection/withdrawal balance, 92 GWh were withdrawn across these storages.
- Gas storages in Germany and two storage locations in Austria (7 Fields and Haidach which are connected to the German transmission grid) are mapped and categorized regarding their prospects to reach the mandatory storage filling levels. Some storages are grouped into clusters if they are geographically close to one another (which is the case at three different locations: EPE, Etzel and Nüttermoor/Jemgum).
- 20 of 48 storages have already reached the target level (dark green category). Many storages are in the light green category, meaning that it is possible to reach the target filling level of the respective storage by November 1 if daily injections are made amounting to 75% of the technical injection capacity or less on average in the period remaining until November 1. Storages requiring daily injections of more than 75% of the technical injection capacity (on average from today until November 1) are in the yellow category.
- Five porous rock storages in Southern Germany can no longer reach the target filling level, even if technical injection capacity was fully used on every remaining day until November 1 (red category). UGS Nüttermoor H-2 and H-5, UGS Rehden and UGS Kiel-Rönne can also no longer fulfill the filling requirements.
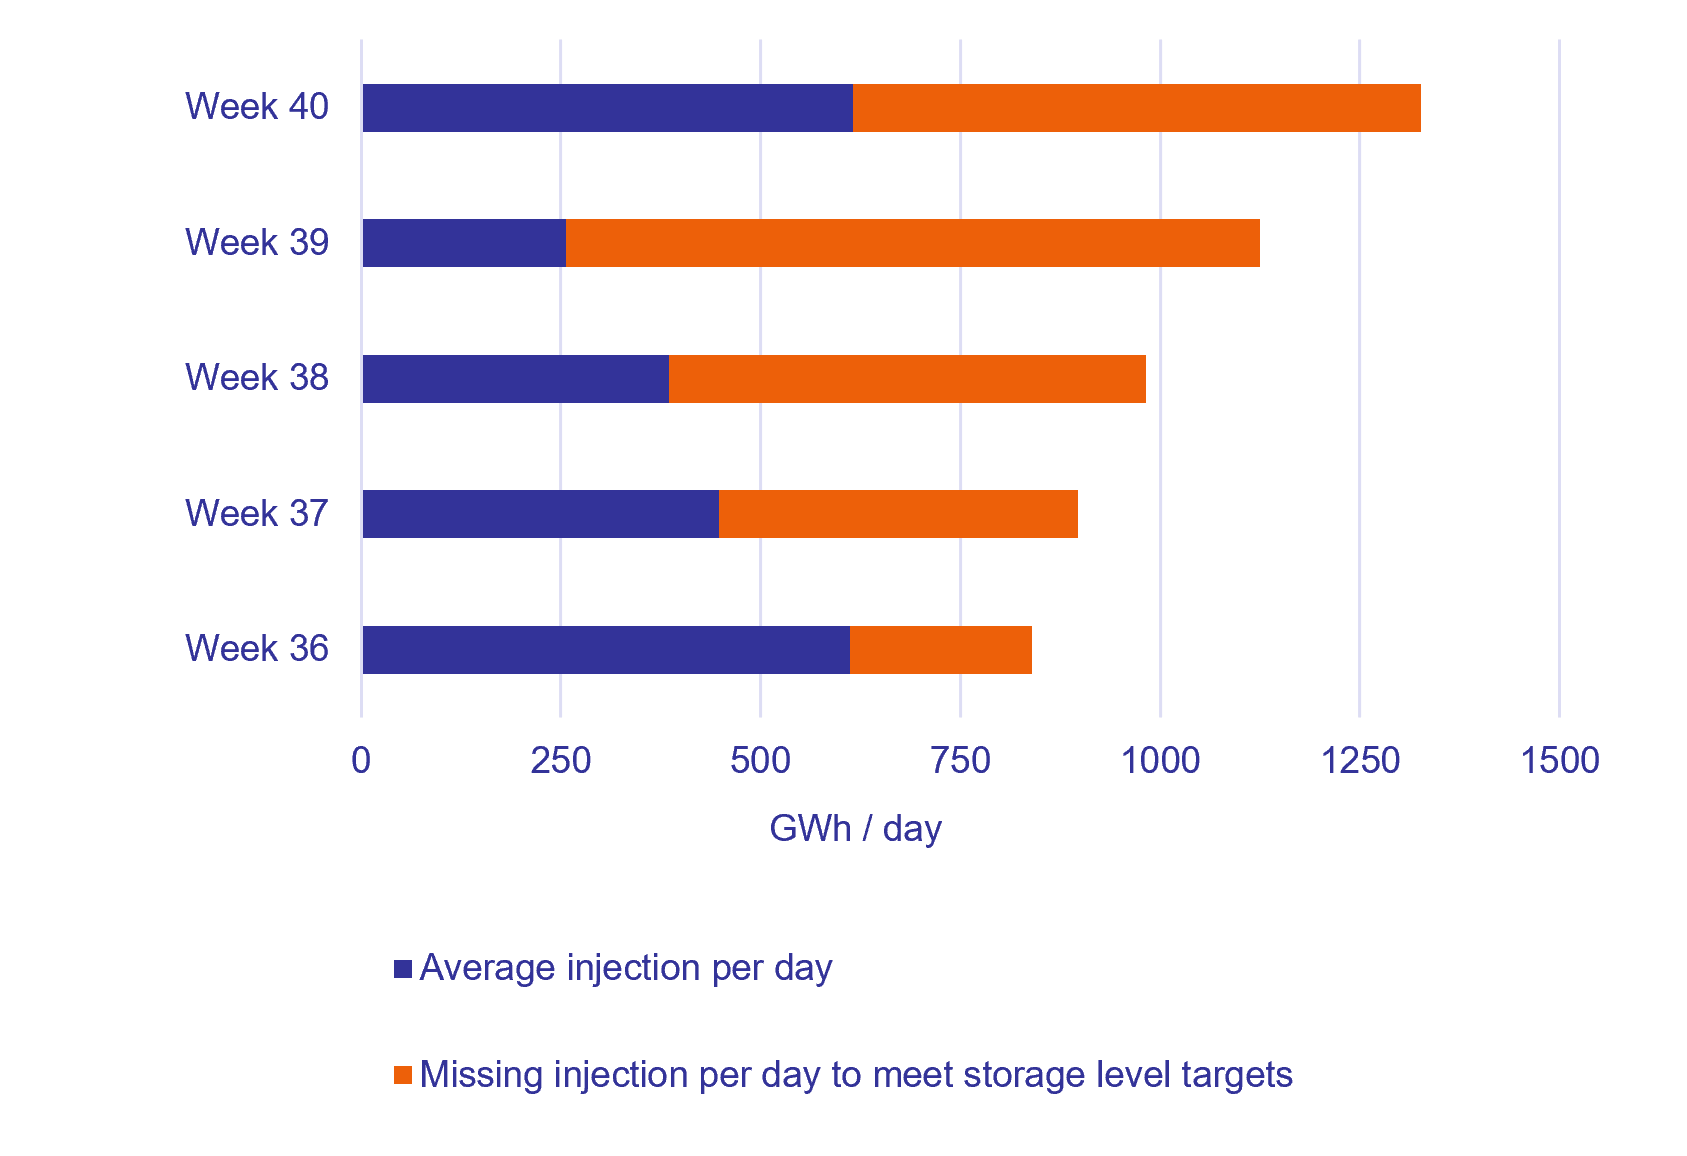
- Daily injections into underground storages in Germany have nearly doubled week-on-week (currently 608.1 GWh/d on average over the past 7 days). The utilization of technical injection capacity remains low (13%). 1326 GWh/d would be required on average until November 1 to meet the targets).
- EEX-THE spot-market price is currently €2.06/MWh lower than the price for Q1’27 contract, incentivizing injection of gas into storage.
- The price spread between JKM and EEX-THE incentivizes LNG deliveries to Asia rather than to Europe: the Asian market shows a premium of €1.76/MWh over Europe for November 2026 and €1.28/MWh for December 2026 (as of October 6).
- In conclusion, the fulfilment of the target filling levels is still technically possible for many storages, however, under given market conditions (price spreads and daily injections) it must be expected that several storages will fail to meet the required filling level by November 1.
- Assuming that the average daily injection remains at the level of the last 7 days, a storage level of just 65.9% would be achievable by 1 November. If the average daily injection remains at the level of the last 21 days, it would be just 64.6%.
Energy Market Radar (12th edition, September 2026)
We have just released the latest version of our Energy Market Radar, this time dealing with the storage situation in Germany. This amounts to a bet on a mild winter and an U.S. president who is more lenient toward Europe and Germany.
In this edition, we show that
- The current average storage level across all storage facilities under review is 57%, and daily injections over the past week (276 GWh/day) have nearly halved compared to the previous week (578 GWh/day)
- Reports of an instruction from the BMWE to SEFE to fill the storage facilities are not supported by the most recent injection figures
- The situation in Southern Germany is significantly more critical than in Northern Germany. Under unfavourable weather conditions (prolonged periods of low wind and little sunlight), this could also become a problem for the gas-based electricity supply, given the installed capacity of 8.5 GW in Bavaria and Baden-Württemberg.
Current filling levels of natural gas storages in Germany
September 2026
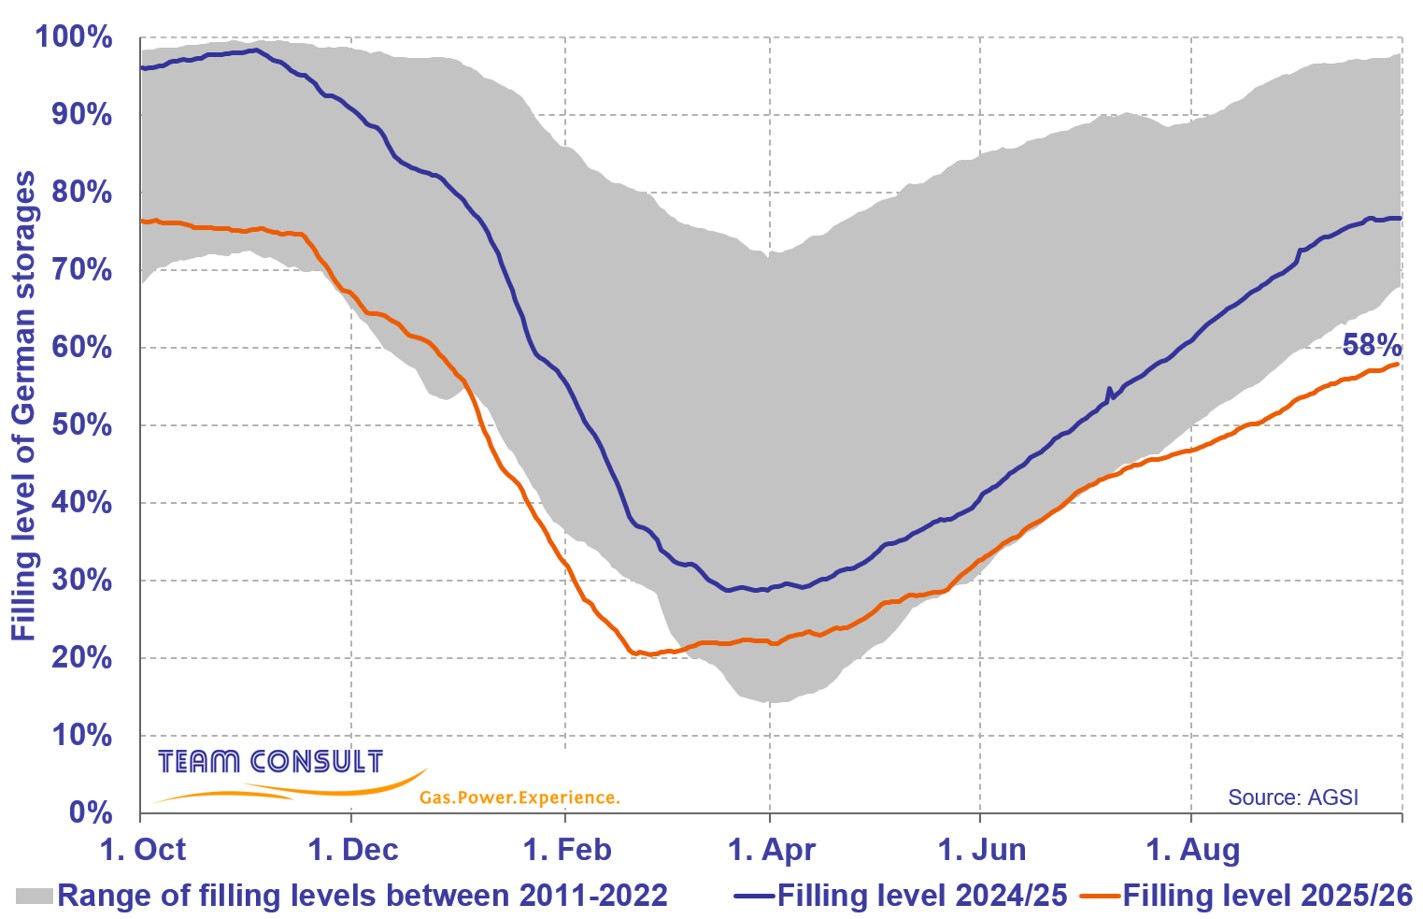
Current filling levels of natural gas storages in Germany
September 2023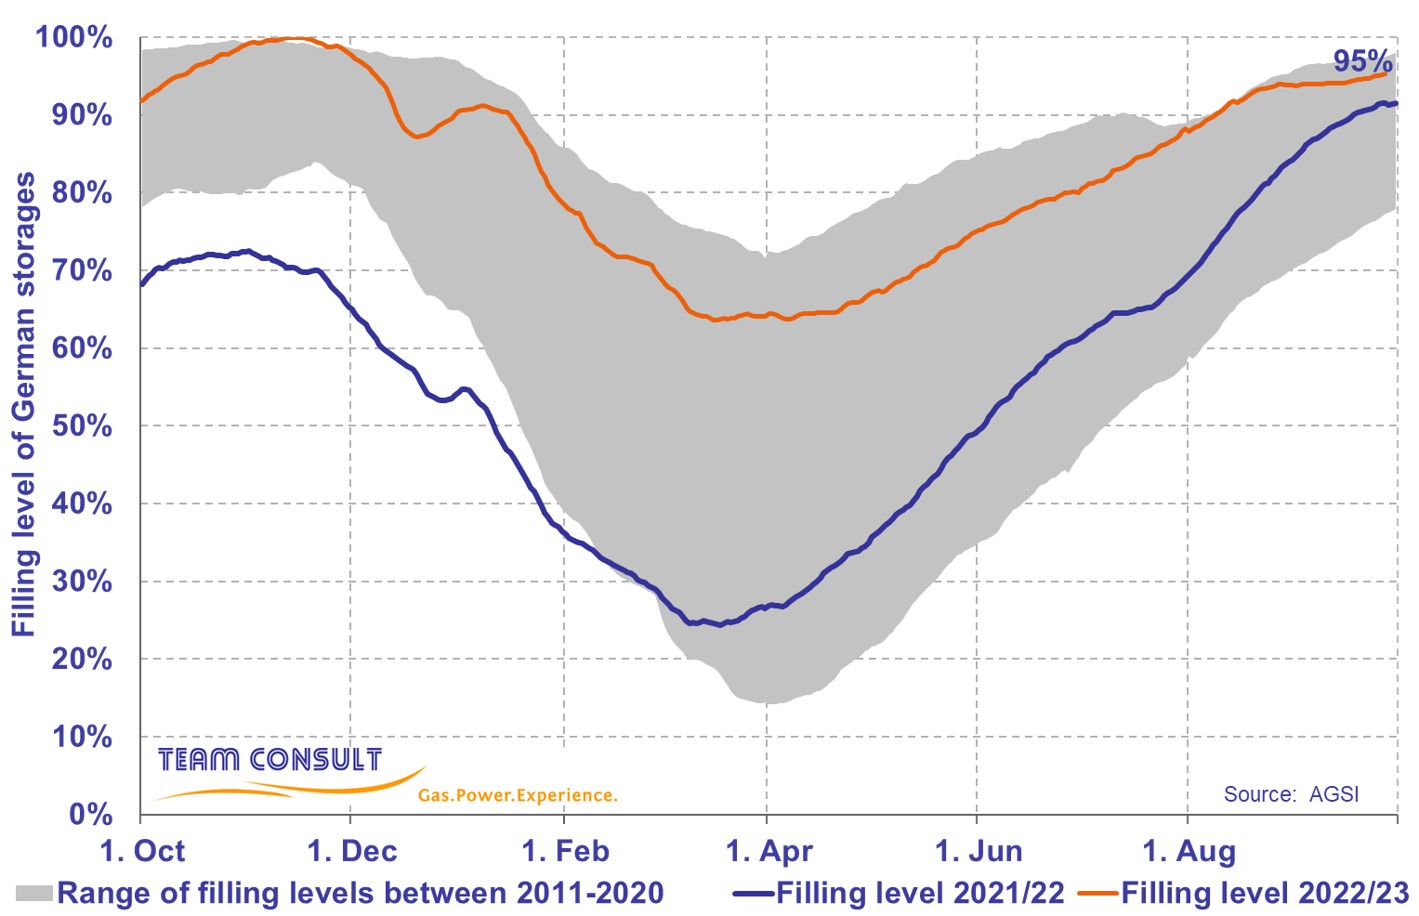
Current filling levels of natural gas storages in Germany
June 2023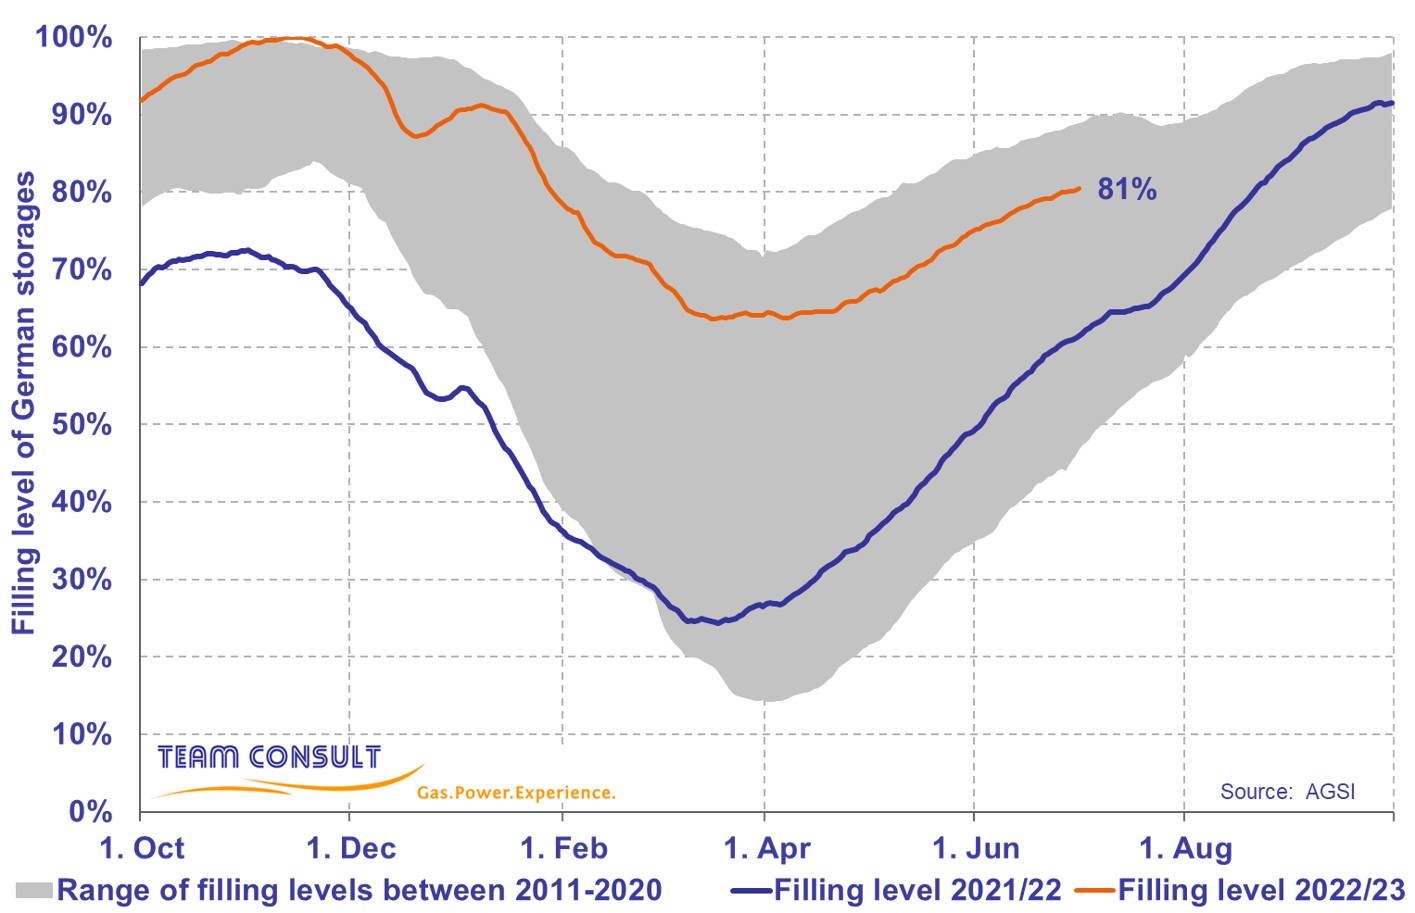
Current filling levels of natural gas storages in Germany
March 2023
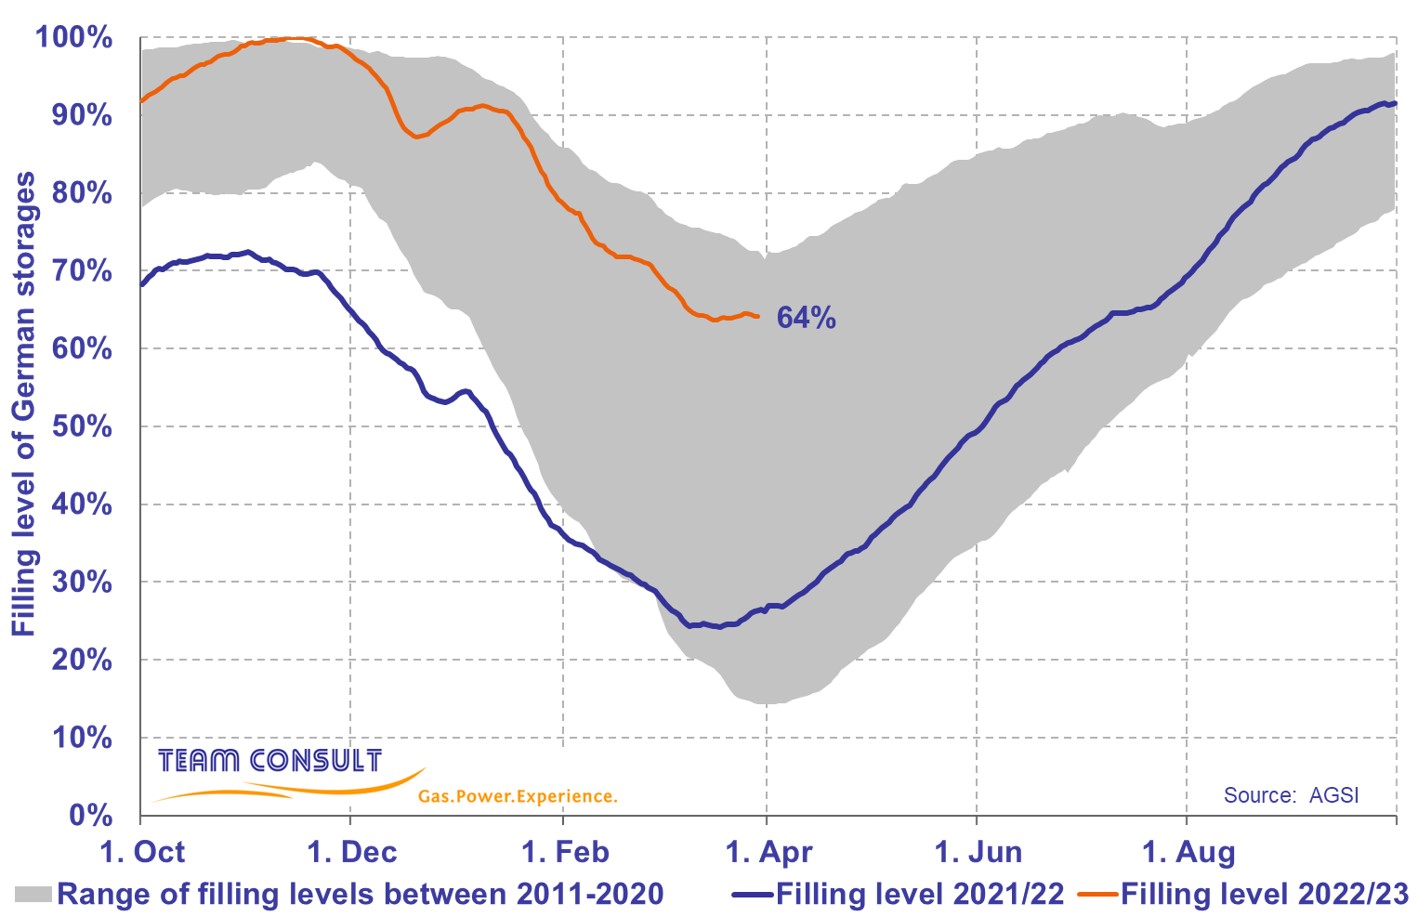
Current filling levels of natural gas storages in Germany
January 2023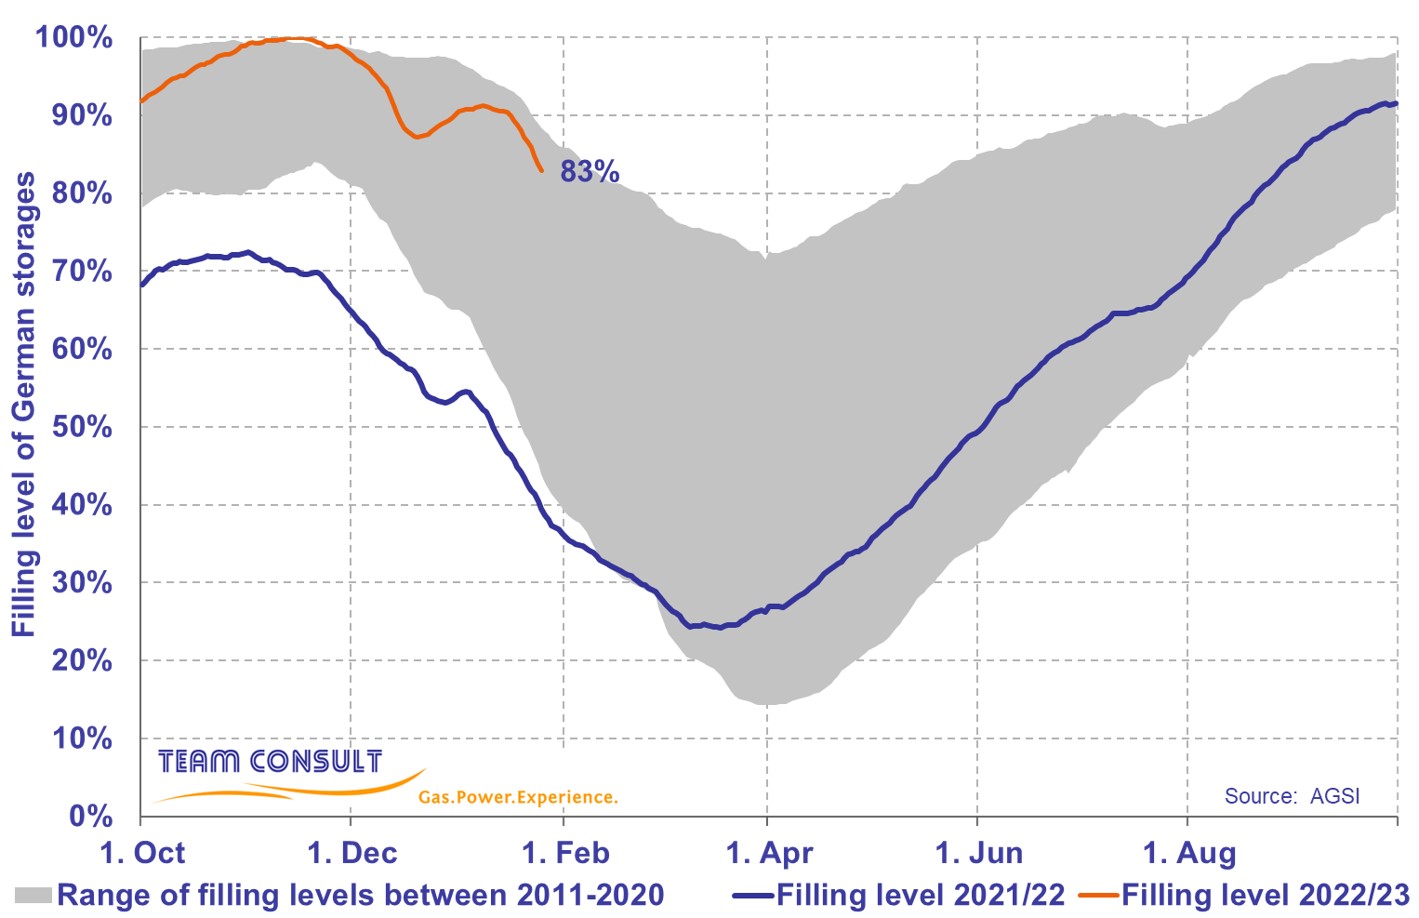
Current filling levels of natural gas storages in Germany
October 2021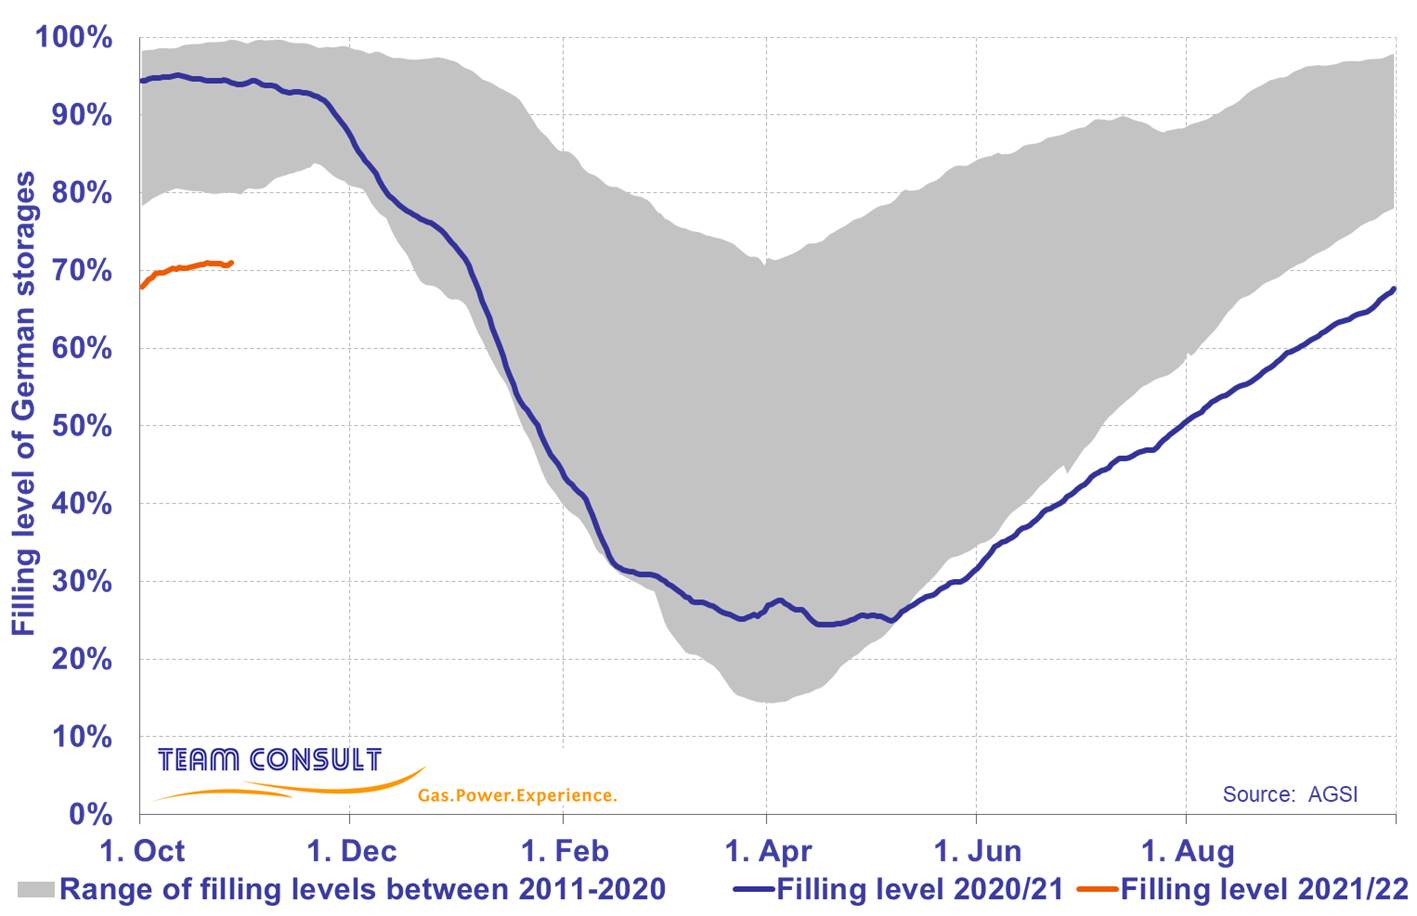
Current filling levels of natural gas storages in Germany
July 2021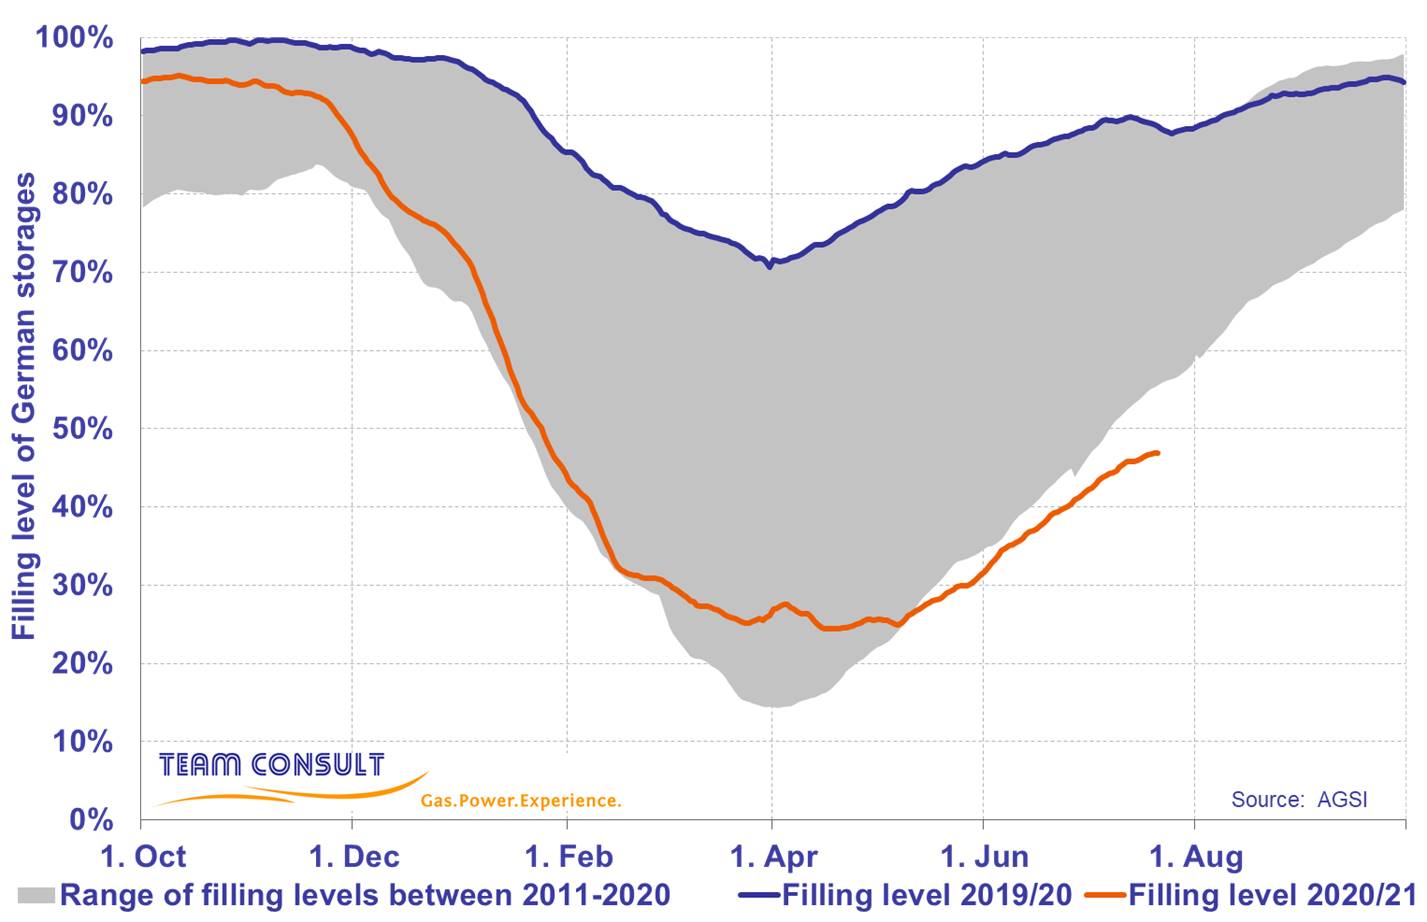
Current filling levels of natural gas storages in Germany
April 2021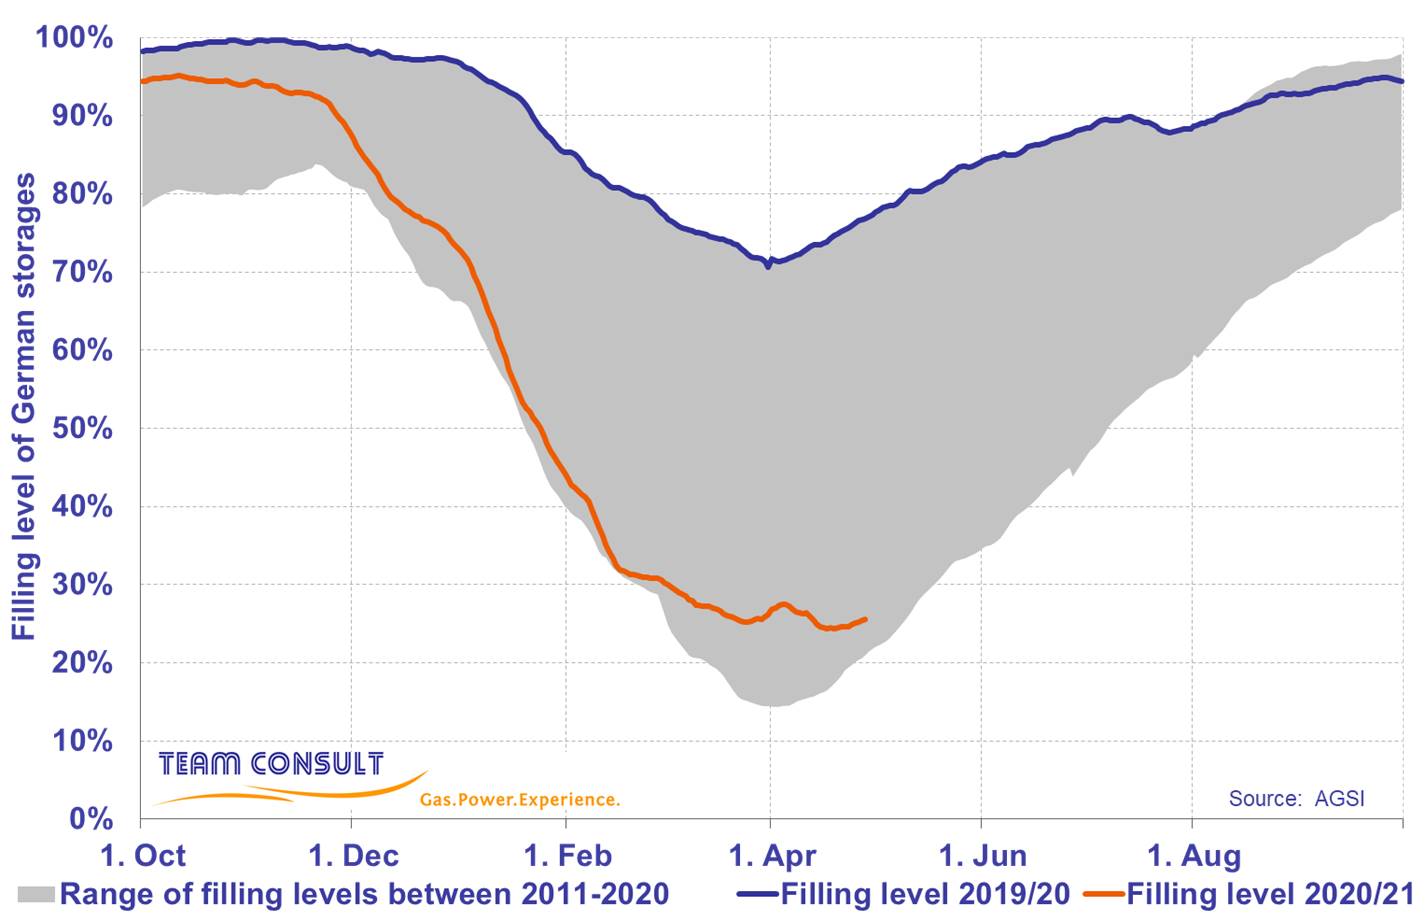
Current filling levels of natural gas storages in Germany
March 2021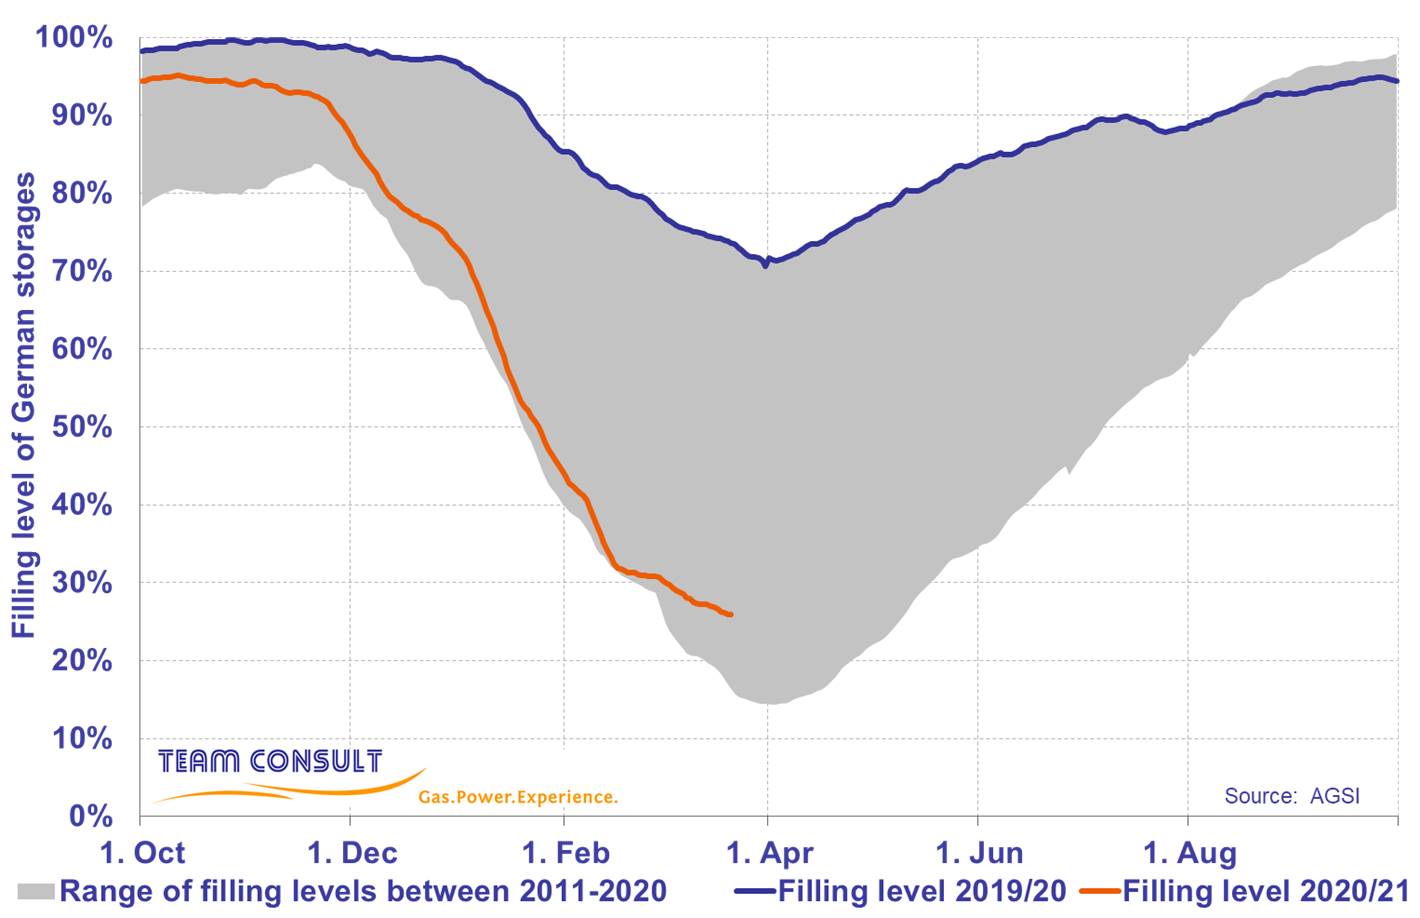
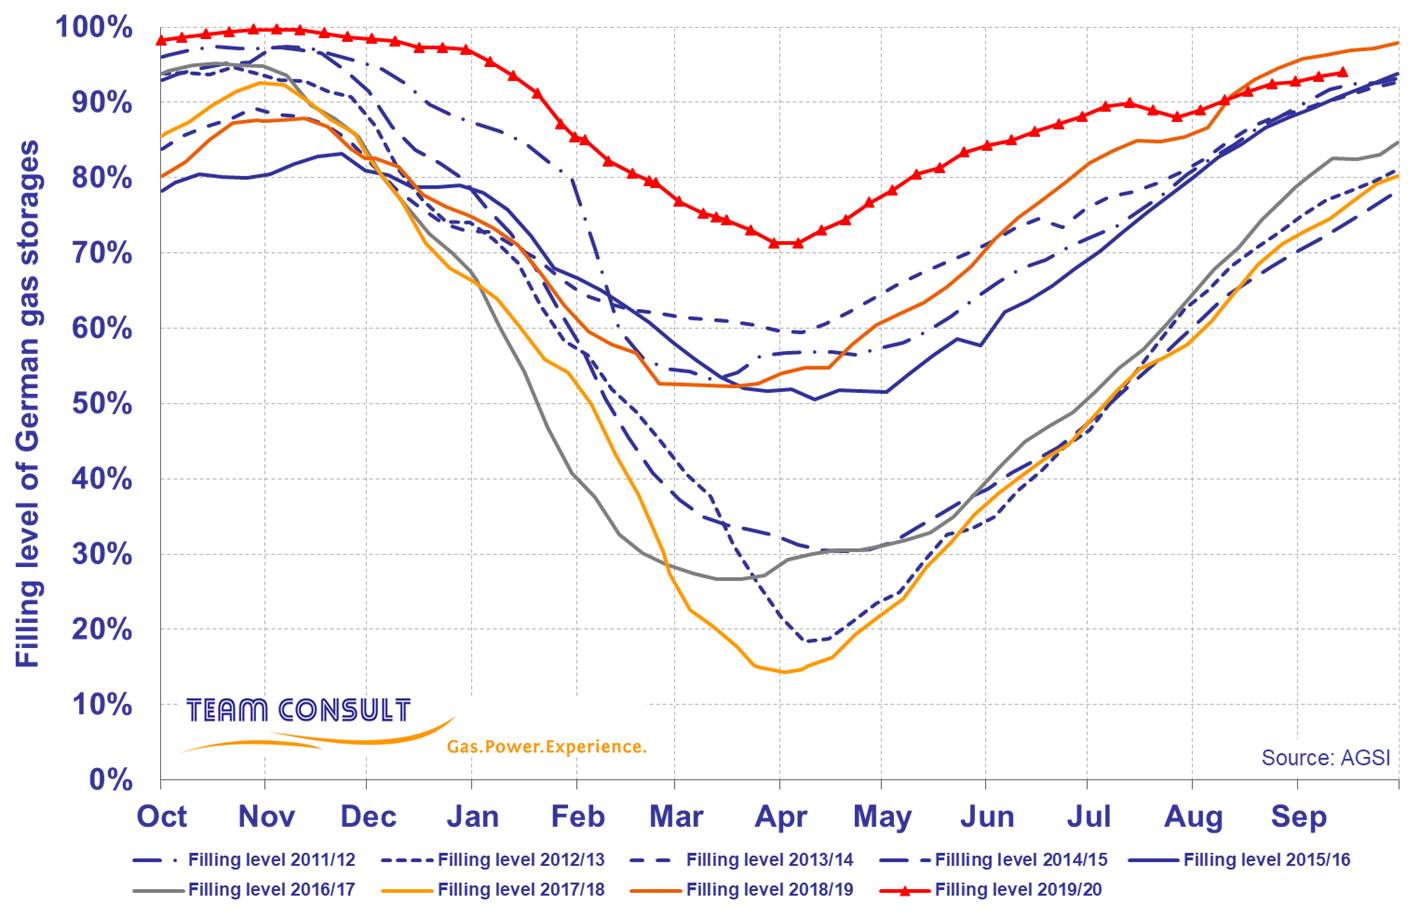
Current filling levels of natural gas storages
September 2020
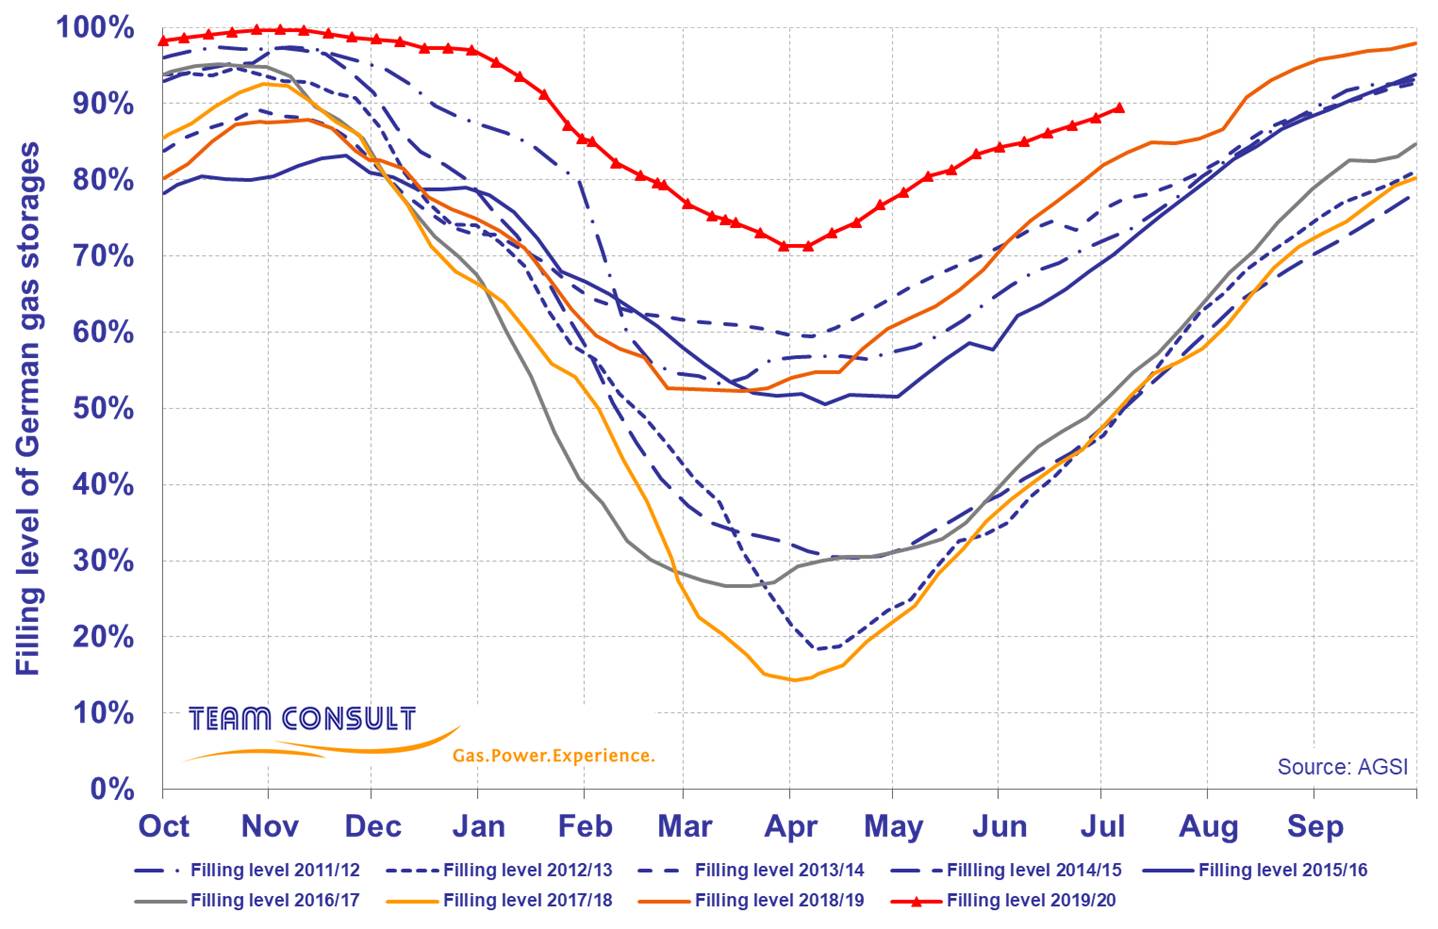
Current filling levels of natural gas storages
June 2020
What happens with the German gas storage filling levels?
February 2020
Preparations for possible supply disruptions caused by a suspension of gas transits via Ukraine were one of the reasons for the high injections into German gas storages throughout the past injection season. At the beginning of the current withdrawal season German gas storage filling levels reached a historic high at above 99% (226 TWh on the basis of AGSI data).
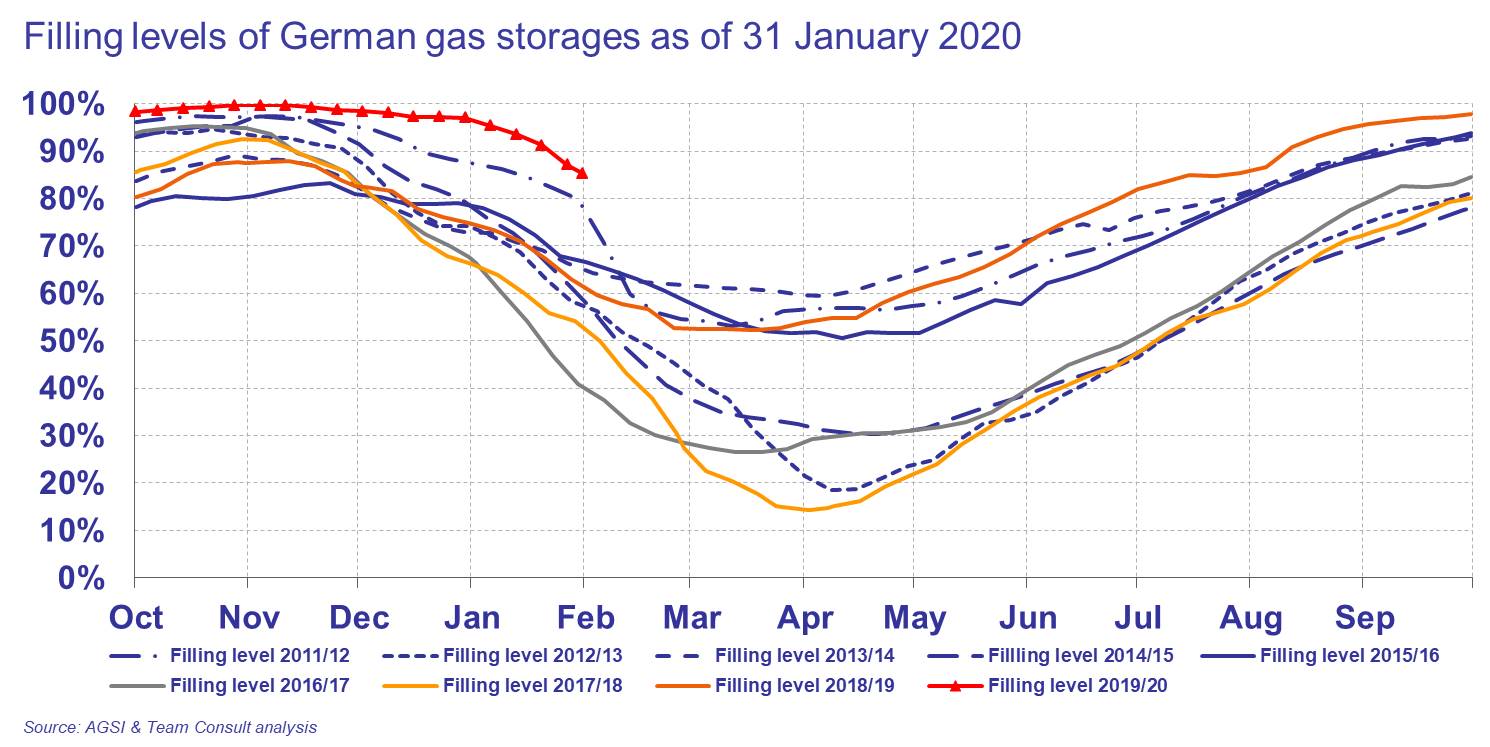
Due to the lack of a cold spell in the current winter 2019/20 storage withdrawals were so far only modest. As a result the filling level of German storages still stood at 87% at the beginning of February. Typically, the filling level is around 55% to 65% at this time of the year.
On the supply side, gas flows from Russia through the Nord Stream pipeline and entries via Mallnow remained constant over the past weeks. Despite an agreement on the transit of gas via Ukraine, gas flows via Ukraine were reduced markedly. Because of low seasonal gas demand and high deliveries from north-west European LNG terminals the supply situation is not affected.
To provide an outlook on the possible storage filling levels at the beginning of April the daily withdrawals of the years 2017/18 (high withdrawals) and 2018/19 (low withdrawals) were used as benchmarks.
- Under the assumption that high storage withdrawals occur throughout the remainder of the winter, a storage filling level of about 100 TWh can be expected.
- By contrast, continued low storage withdrawals would lead to a storage filling level of about 170 TWh by the end of winter.
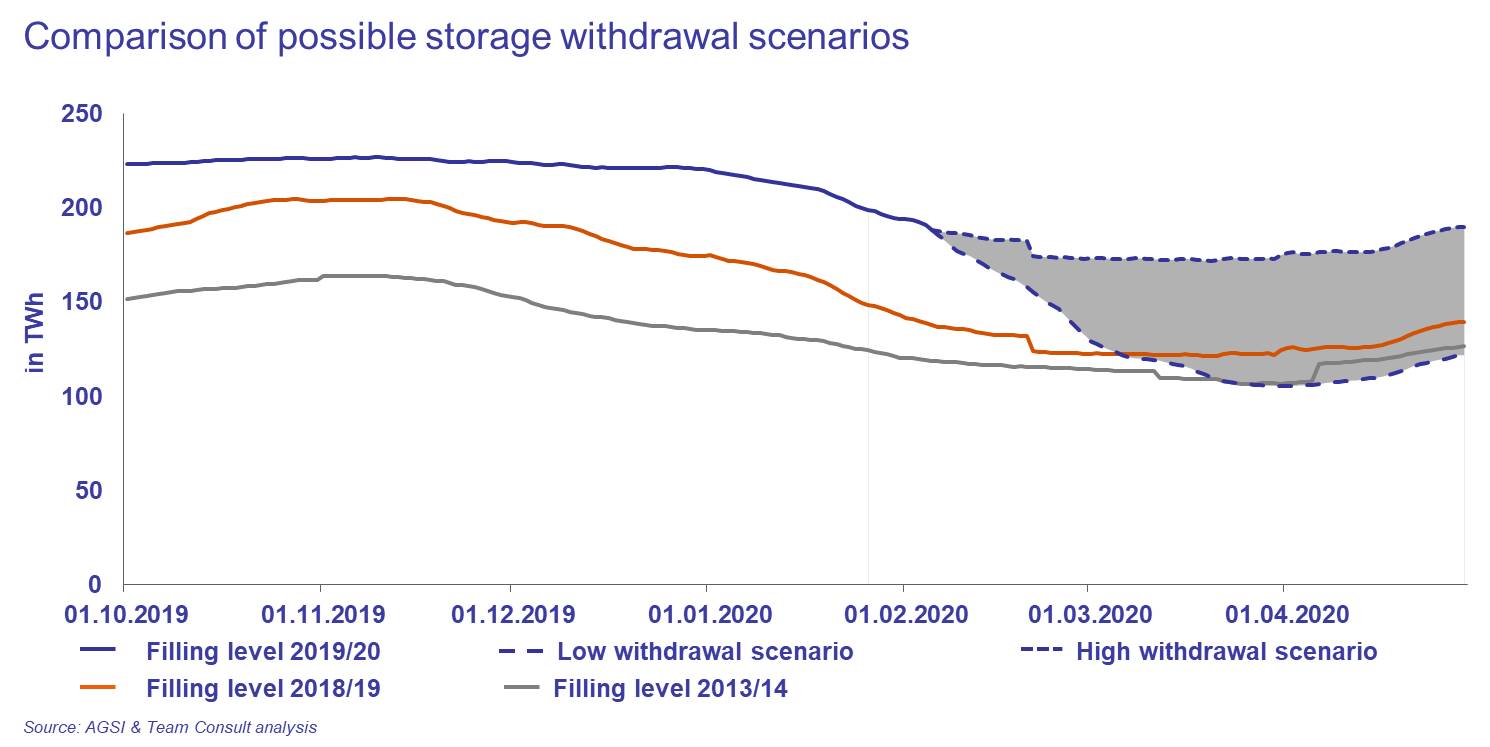
By contrast, continued low storage withdrawals would lead to a storage filling level of about 170 TWh by the In the latter case a lower gas demand in the coming summer can be expected. Provided that the supply situation remains good this situation will increase the pressure on wholesale gas prices so that even historically low prices would not come as a surprise. A similar situation occurred in the years 2014 and 2019 which were marked by high storage levels at the end of winter. This led to low wholesale prices during the summer. Under these preconditions a high utilisation of gas fired power plants can be expected.end of winter.
Filling levels of natural gas storages in January 2019
February 2019
At the beginning of January, German gas storage facilities had an aggregated filling level of 75 percent (174 TWh), a good 9 percentage points above the previous year's level. Over the course of the month, the level fell by 12 percentage points to 61 percent (142 TWh). This figure was still a good 9 percentage points above the level at the same time last year.
Looking at the daily withdrawals, January showed a divided picture. In the first half of the month, up to 1.4 TWh per day were withdrawn at peak times. In the second half of the month, temperatures dropped and withdrawals increased significantly, peaking at up to 2.1 TWh per day.
Regulatory matters
Strategy development
Brochures